Note: This article concerns a rule scheduled to take effect on 15 October 2026. We keep the publication and last-updated dates visible above, and this page will be revised if NPCI, the Ministry of Finance, RBI or another competent authority changes the framework before or after implementation.
Will you have to pay extra if you make a ₹5,000 UPI payment? What happens when you scan a shop's QR code for ₹10,000? And does the new UPI ₹2,000 rule mean UPI is no longer free?
These questions have started attracting significant attention after the announcement of a revised Merchant Discount Rate, or MDR, framework for certain UPI transactions from 15 October 2026.
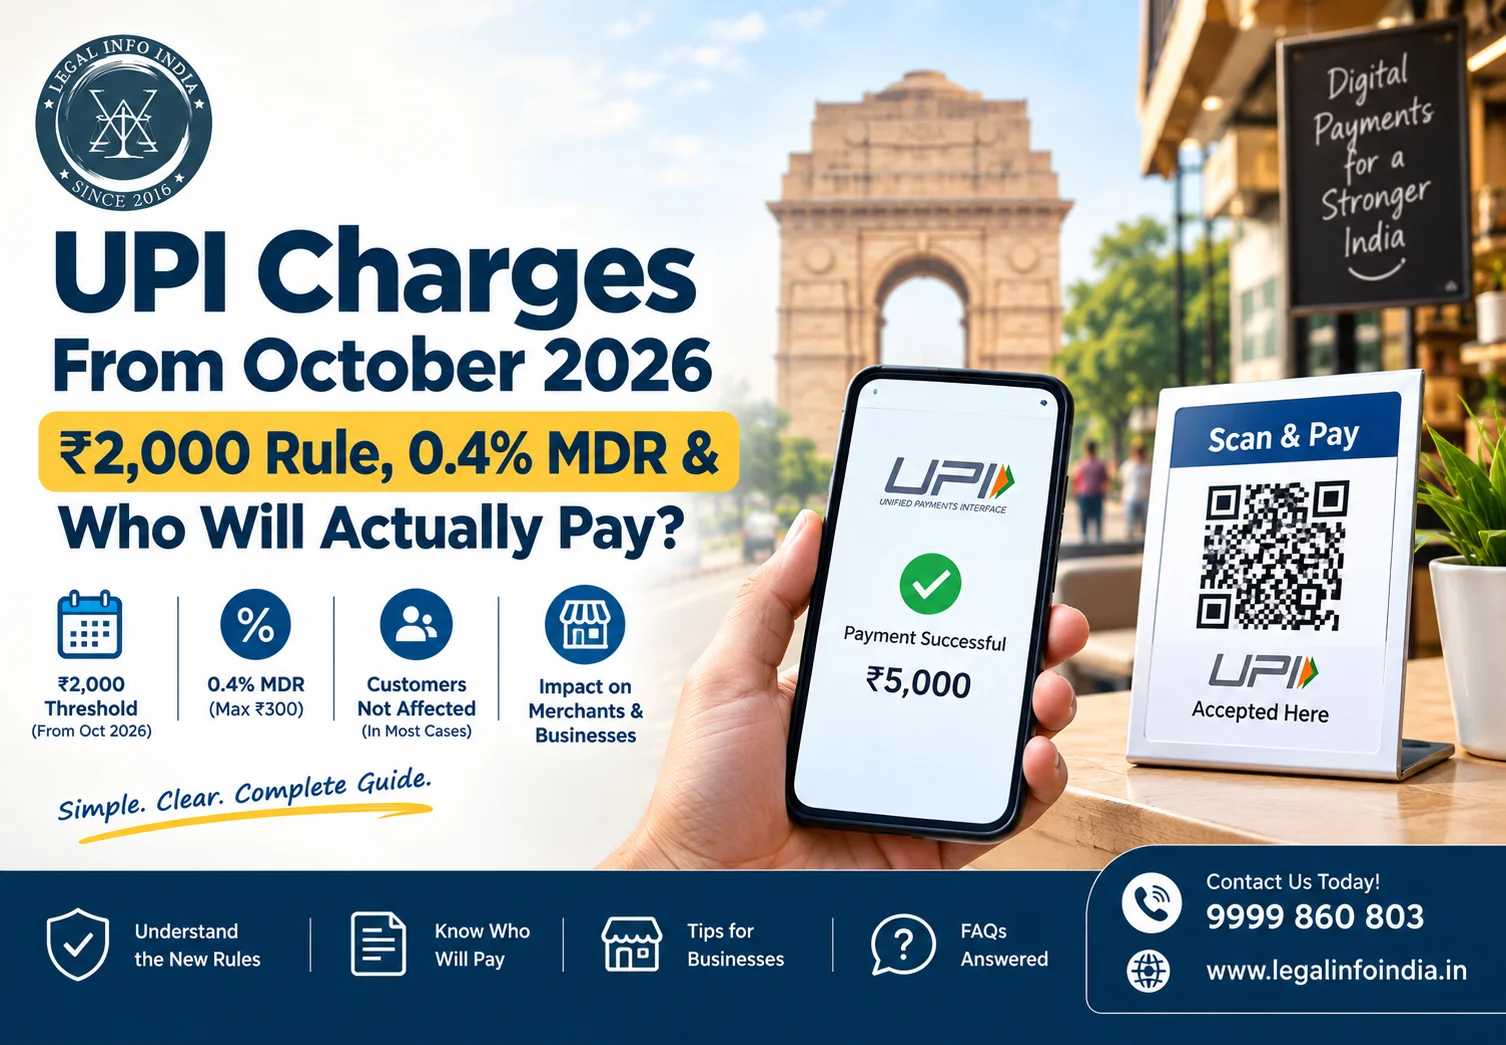
The headline numbers are easy to remember: ₹2,000 threshold, 0.4% MDR and a maximum ₹300 cap for applicable high-value transactions. But the headline alone can create the wrong impression.
The new framework does not mean that every person sending more than ₹2,000 through UPI will automatically be charged 0.4%. The framework primarily concerns specified person-to-merchant (P2M) transactions. Person-to-person, or P2P, UPI transactions remain free, while payments to merchants up to ₹2,000 also remain free. Small merchants covered by the zero-MDR framework can also continue without MDR.
For consumers, businesses, retailers, online sellers and service providers, understanding this distinction is important.
This guide from Legal Info India explains the UPI Charges 2026 framework in simple terms, including who pays MDR, what the ₹2,000 rule actually means, how the 0.4% calculation works, which transactions have special treatment and what businesses should review before the new framework takes effect.
From 15 October 2026, a revised MDR framework is scheduled to apply to specified UPI merchant transactions. The key change is that eligible P2M transactions above ₹2,000 can attract a 0.4% MDR, subject to the applicable category rules and a maximum of ₹300 per transaction for transactions of ₹75,000 and above.
At the same time, several categories remain outside this standard MDR structure. According to the Ministry of Finance:
Person-to-person UPI transactions remain free, irrespective of the amount.
Merchant payments up to ₹2,000 remain free of MDR.
Eligible small merchants receiving up to ₹1 lakh per month through UPI QR under the specified P2PM framework continue with zero MDR.
Certain essential sectors have a flat ₹5 MDR for applicable transactions above ₹2,000.
Capital market transactions have a separate 0.02% MDR, subject to a ₹300 cap.
The government has also clarified that MDR is not a government tax or a fee collected by the government or NPCI. It is a charge within the payment ecosystem and is distributed among participating entities such as banks and payment service providers.
The first thing to understand is that ₹2,000 is not a universal UPI transaction limit. A person can still use UPI for transactions above ₹2,000. The ₹2,000 threshold is relevant to the MDR treatment of specified merchant transactions.
For example, suppose you purchase goods from a large merchant and pay ₹1,500, ₹2,000, ₹5,000 or ₹10,000 through UPI. The transaction amount alone does not mean that the customer must pay an additional UPI fee. Instead, the applicable MDR depends on the nature of the transaction, the merchant's classification and the relevant category under the new framework.
This distinction is particularly important because the phrase "UPI charges above ₹2,000" can otherwise be misunderstood as meaning that UPI users are being charged simply for sending more than ₹2,000. They are not.
MDR stands for Merchant Discount Rate. In simple terms, MDR is a charge associated with processing certain merchant payment transactions. Under the new framework, the applicable MDR is part of the payment ecosystem rather than a general fee imposed on the individual making a UPI payment. The government has specifically stated that customers will not pay MDR for standard UPI transactions covered by the framework.
Think about a simple example. A customer buys products worth ₹5,000 from an eligible merchant and pays through UPI. At 0.4%: ₹5,000 × 0.4% = ₹20. So, where the transaction falls within the applicable MDR category, the merchant-side MDR would be ₹20. That does not mean the customer should automatically see ₹5,000 + ₹20 = ₹5,020 as their UPI payment. The government has advised banks and payment ecosystem participants to ensure that the MDR is not passed on to customers.
For specified P2M transactions above ₹2,000, the baseline MDR is 0.4%. There is also a ₹300 maximum MDR per transaction for transactions of ₹75,000 and above. Here are some simple illustrations of how the standard 0.4% structure would apply:
| Payment to Eligible Merchant | 0.4% Calculation | Illustrative MDR |
|---|---|---|
| ₹2,500 | ₹10 | ₹10 |
| ₹5,000 | ₹20 | ₹20 |
| ₹10,000 | ₹40 | ₹40 |
| ₹25,000 | ₹100 | ₹100 |
| ₹50,000 | ₹200 | ₹200 |
| ₹75,000 | ₹300 | ₹300 |
| ₹1,00,000 | ₹400, subject to cap | ₹300 |
These examples are only illustrations of the standard 0.4% structure. The actual treatment can differ where the transaction falls into a special category or exemption. For example, specified essential sectors such as railways, telecommunications, insurance, fuel and agricultural inputs have a flat ₹5 MDR for applicable transactions above ₹2,000. Capital-market payments have a separate 0.02% MDR, capped at ₹300.
This is probably the most important question surrounding the new UPI rules. The revised MDR is not a blanket consumer transaction fee. The Ministry of Finance has clarified that customers will not be required to pay MDR for the applicable UPI transactions. P2P transactions remain completely free, regardless of the amount transferred. Merchant payments up to ₹2,000 also remain free of MDR.
The distinction can be understood like this:
Customer → Friend: ₹10,000 UPI transfer — No MDR under this framework.
Customer → Eligible Merchant: ₹10,000 UPI payment — Merchant-side MDR may apply, depending on the applicable category.
Therefore, the words "UPI charges" can be misleading when used without explaining who is actually being charged.
Here is a simple way to understand the new framework:
| UPI Payment | What the User Should Understand |
|---|---|
| ₹500 | No general consumer UPI fee |
| ₹2,000 | Merchant payment remains within the zero-MDR threshold |
| ₹2,500 | Eligible merchant MDR rules may apply |
| ₹5,000 | Merchant-side MDR may apply depending on category |
| ₹10,000 | Same principle, subject to merchant and transaction category |
| ₹10,000 to a friend | P2P transaction remains outside the MDR framework |
The key question is therefore not simply "Is the payment above ₹2,000?" It is "What type of UPI transaction is it, and does the applicable merchant/category fall within the MDR framework?" That is why businesses should understand their payment classification rather than assuming that every transaction above ₹2,000 will automatically attract the same charge.
This is particularly relevant for India's neighbourhood businesses, street vendors and small retailers. The Ministry of Finance has stated that small merchants receiving up to ₹1 lakh per month through UPI QR under the specified P2PM category will continue to enjoy zero MDR.
This means a small vendor can potentially receive a customer payment above ₹2,000 without standard MDR applying if the merchant qualifies under the applicable zero-MDR framework. Business Standard has also reported that the P2PM classification is important for determining whether a small merchant qualifies for zero MDR.
Therefore, a shopkeeper should not assume: "A customer paid more than ₹2,000, so I automatically have to pay 0.4%." The merchant's applicable classification and monthly UPI receipts also matter.
Not every UPI payment above ₹2,000 falls into the standard 0.4% category. The official government clarification identifies several categories.
P2P UPI transactions remain completely free regardless of the amount transferred.
P2M payments up to ₹2,000 remain free of MDR.
Eligible small merchants receiving up to ₹1 lakh per month through UPI QR under the specified P2PM category continue with zero MDR.
Specified sectors including railways, telecommunications, insurance, fuel and agricultural inputs have a separate flat ₹5 MDR for applicable transactions above ₹2,000.
Payments relating to mutual funds, securities, stockbrokers and dealers have a separate 0.02% MDR, capped at ₹300 per transaction.
This is why simply saying "UPI above ₹2,000 will cost 0.4%" is incomplete.
This is one of the concerns that has emerged around the new UPI MDR framework. Some traders have expressed concerns that MDR could increase payment costs and affect already narrow business margins. Reports from different markets have also described some merchants considering restrictions on high-value UPI payments or requesting cash instead. These are reported reactions from particular merchant groups, not a statement that all merchants will stop accepting UPI.
The government, meanwhile, has emphasized that the MDR should not be transferred to customers. It has also indicated that monitoring will focus on implementation and whether charges are passed on to consumers.
For consumers, this creates an important practical distinction. MDR and customer surcharge are not the same thing. If an eligible merchant incurs MDR on a transaction, that does not automatically mean the merchant can simply add a separate "UPI charge" to the customer's bill. The government has advised banks to ensure that merchants do not pass the new charges to customers.
Whether an individual merchant chooses to restrict UPI acceptance for certain transactions can be a separate commercial matter, but it should not be confused with the MDR itself becoming a consumer fee.
The change is particularly relevant for businesses that receive a substantial volume of digital payments. These can include:
E-commerce businesses
Online sellers
Retail stores
Restaurants
Service providers
Professional firms
Subscription businesses
Education and training businesses
Large merchants
Marketplaces
Businesses using payment aggregators
For such businesses, payment costs can become part of the overall cost of doing business. A business should therefore understand:
Its UPI merchant category
Whether it falls within the applicable zero-MDR framework
Its monthly UPI receipts
The MDR applicable to its transaction category
The terms offered by its bank or payment service provider
How payment charges are reflected in accounting records
Whether invoices and billing practices remain compliant
For businesses already maintaining formal accounts, this is another reason to keep payment records properly reconciled.
The new MDR framework also raises a broader question about payment choices. A simple factual comparison looks like this:
| Factor | UPI | Cash | Card |
|---|---|---|---|
| Digital record | Yes | No | Yes |
| Physical handling | No | Yes | No |
| Merchant-side charges | Depends on transaction/category | Generally no MDR | Usually applicable |
| Convenience | Digital | Physical cash required | Digital |
| Transaction record | Available electronically | Requires separate records | Available electronically |
This does not mean that one payment method will replace another. The actual choice can depend on transaction value, merchant policy, customer preference, business costs, infrastructure and applicable rules.
Businesses accepting UPI payments can use the period before implementation to review their payment arrangements.
Do not assume that every business is treated identically.
If your business may qualify for zero MDR under the P2PM framework, confirm the applicable classification with your bank or payment service provider.
Businesses using payment gateways, aggregators or other payment service providers should review the updated commercial terms applicable to their account.
Businesses should avoid automatically adding a separate line item called "UPI MDR" to customer invoices without first establishing whether such recovery is permitted.
Keep UPI receipts, settlement reports, invoices and accounting records properly reconciled.
If your business operates in fuel, insurance, telecom, railway-related services, agricultural inputs, capital markets or another specially treated category, check the specific MDR applicable to that transaction type.
For growing businesses, payment compliance is only one part of the legal and financial structure. Depending on the business, this can include:
Proper invoicing
Accounting and tax compliance
This is particularly relevant for startups and growing businesses receiving payments from customers across India.
The answer requires some qualification. UPI is not becoming universally chargeable. The revised framework introduces MDR for specified merchant transactions above ₹2,000, while P2P transactions remain free, merchant payments up to ₹2,000 remain free, and eligible small merchants continue under the zero-MDR framework. The government estimates that approximately 96% of P2M transactions will remain unaffected.
So the more accurate description is: a specific segment of UPI merchant transactions is moving from the earlier zero-MDR structure to a defined MDR framework. That is considerably different from saying "UPI users will now have to pay for UPI."
According to the Ministry of Finance, the revised framework is intended to support the long-term sustainability of the UPI ecosystem while protecting individuals and small merchants from additional charges.
UPI involves a large technology and financial infrastructure involving banks, payment service providers, applications and other participants. The new framework therefore creates a mechanism for specified merchant transactions to contribute to the payment ecosystem's operating costs.
The policy debate around the change includes questions about merchant costs, digital-payment adoption and the possible effect on cash usage. Those are matters that businesses, industry bodies and policymakers may continue to discuss as implementation begins.
For an ordinary UPI user, the most important points are straightforward. You do not need to assume that a payment above ₹2,000 will result in a 0.4% fee being deducted from your bank account. Instead:
P2P UPI remains free
P2M payments up to ₹2,000 remain free of MDR
Eligible small merchants can remain under zero MDR
Specified merchant transactions above ₹2,000 can attract MDR
The standard MDR is 0.4% for the applicable category
MDR is capped at ₹300 for transactions of ₹75,000 and above
Certain sectors have separate flat or reduced rates
The government has stated that MDR should not be passed on to customers
The biggest takeaway is therefore simple: ₹2,000 is an MDR threshold for specified merchant transactions, not a universal UPI payment limit.
For a growing business, changes in digital payment rules are often a reminder to review the overall legal and compliance structure. Legal Info India assists entrepreneurs, startups, retailers, professionals and businesses with various registration and compliance-related services. Depending on the nature and stage of your business, this may include:
Startup and business registration guidance
Trademark Objection and Opposition
International Trademark Registration
Trademark Rectification
For example, a startup accepting UPI payments may need to think beyond payment collection. Its legal structure, GST requirements, business identity, brand protection and applicable registrations may all need to be reviewed separately.
If you are planning to establish a new business, you can also explore Online Company Registration in Delhi and other business registration services according to your business structure and requirements.
For the strongest factual references on this topic, refer to:
Press Information Bureau (PIB) — for the Ministry of Finance's official clarification on the revised UPI MDR framework
National Payments Corporation of India (NPCI) — for official UPI operating guidelines and circulars

The discussion around UPI Charges 2026 is much more nuanced than the headline "UPI above ₹2,000 will be charged."
From 15 October 2026, the revised framework introduces a 0.4% MDR for specified P2M UPI transactions above ₹2,000, with a ₹300 cap for transactions of ₹75,000 and above. But P2P transactions remain free, merchant payments up to ₹2,000 remain free, and eligible small merchants continue under zero MDR. Certain essential sectors and capital-market transactions also have separate treatment.
Most importantly, the MDR should not be confused with a direct UPI fee charged to customers.
For customers, the practical question is whether a merchant is covered by the applicable MDR framework. For businesses, the important questions involve merchant classification, transaction category, payment-provider terms, accounting and billing practices.
As implementation approaches, businesses should rely on official notifications, NPCI/payment-provider communications and their professional advisers for transaction-specific compliance questions.
For business registration, GST, MSME, FSSAI and trademark-related assistance, Legal Info India provides registration and compliance support for entrepreneurs and businesses in Delhi and across India.
Not universally. The ₹2,000 threshold applies to specified merchant transactions under the MDR framework. P2P transactions remain free, while P2M payments up to ₹2,000 remain free of MDR.
The revised MDR is a merchant-side payment ecosystem charge, not a blanket fee payable by the customer. The government has advised banks and payment participants to ensure the MDR is not passed on to customers.
MDR means Merchant Discount Rate. It is a charge associated with processing certain merchant payment transactions. Under the new framework, applicable MDR is distributed among participants in the payment ecosystem.
It refers to the threshold used in the revised MDR framework for specified person-to-merchant transactions. It is not a universal ₹2,000 limit on UPI payments.
The revised framework is scheduled to apply from 15 October 2026.
No. Person-to-person UPI transactions remain completely free under the framework, regardless of the amount transferred.
Eligible small merchants receiving up to ₹1 lakh per month through UPI QR under the specified P2PM framework continue with zero MDR. The actual classification should be confirmed with the relevant payment provider.
The government has advised banks and payment participants to ensure that MDR is not passed on to customers. A merchant should therefore not automatically treat MDR as a customer surcharge.
That cannot be determined in advance. The framework affects a defined segment of merchant transactions, while the government says approximately 96% of P2M transactions will remain unaffected. Industry and merchant reactions may continue to evolve after implementation.
Businesses do not necessarily need to abandon UPI. They should first understand their merchant category, applicable MDR, payment provider terms and accounting implications, and then evaluate their payment arrangements based on their own business requirements.
We prioritize understanding your unique situation & offer tailored strategies that align with your goals,
don't navigate the legal maze alone – schedule.

Call Us 24/7
+91 9999 860 803
Call Us 24/7
+91 8527 406 788
Mail Us Anytime
info@legalinfoindia.in
Mail Us Anytime
nrandassociate@gmail.com
© Copyright 2025 LegalInfoIndia
Developed By:Vairina Infotech


 15 Sep 2026 (Last updated: 20 Sep 2026)