Note: This article summarises GST Council recommendations announced on 8 October 2026. They are recommendations, not automatically operative law, and the article distinguishes them from amendments that have legally taken effect. The publication and last-updated dates are shown above, and the article will be revised as legislation, notifications, circulars or portal instructions are issued, particularly for changes scheduled for November 2026 and April 2027. It is for general information and is not a substitute for professional advice.
Introduction: What Businesses Should Know About GST Compliance Changes 2027
GST compliance in India is moving towards a more technology-driven system, with greater emphasis on accurate return reporting, easier reconciliation, faster processing of eligible refunds and more predictable procedures.
For businesses, these changes could have a direct impact on working capital, accounting processes, input tax credit (ITC), return filing and the way GST-related discrepancies are resolved.
At its 57th meeting on 8 October 2026, the GST Council recommended a series of process reforms intended to reduce compliance difficulties for taxpayers. The recommendations cover GST return corrections, ITC reconciliation, automated refund processing, registration procedures, certain refund eligibility rules and dispute-related processes.
One of the most significant proposals is an alternative mechanism for correcting certain differences between GST liability and ITC reported across returns. The Council recommended bringing this mechanism into force from the April 2027 return period, subject to the required implementation steps.
The refund proposals are intended to be introduced in phases. They include faster acknowledgement of refund applications, automated provisional refunds for specified eligible claims and broader system-based processing.
These developments matter to manufacturers, traders, service providers, exporters, e-commerce sellers, startups and small businesses that depend on predictable GST compliance.
However, there is an important distinction: a GST Council recommendation is not automatically an operative legal rule. Businesses must check the relevant amendments, notifications, rules and GST portal instructions before relying on a proposed facility.
This guide explains the key GST Compliance Changes 2027, what the proposed reforms may mean in practice, and the steps businesses can take now to prepare.
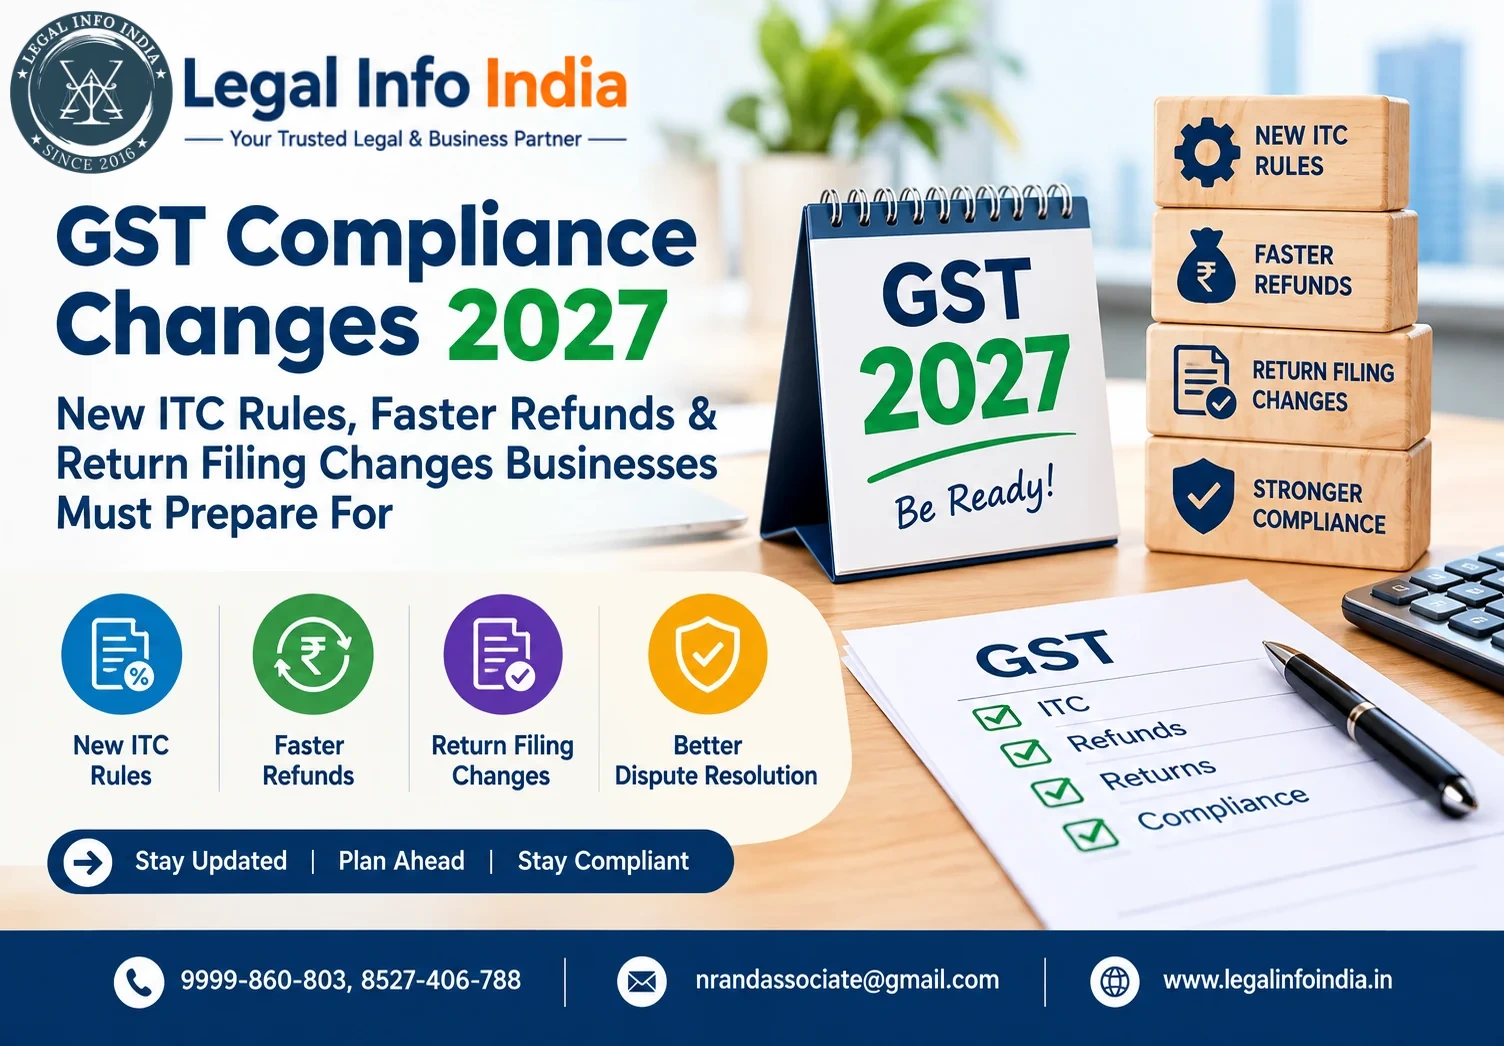
The proposed reforms focus on reducing avoidable errors, improving transparency and making selected GST procedures more predictable.
Here is a quick overview of the main areas.
| Area | Proposed change | Why it matters |
|---|---|---|
| GST returns | Better alignment between GSTR-1, GSTR-1A, IFF and GSTR-3B | Fewer unexplained liability mismatches |
| Input tax credit | Improved reconciliation with GSTR-2B and better tracking of reversals and reclaims | More reliable ITC reporting |
| Refunds | Phased system-based acknowledgement and processing | Potentially faster access to eligible funds |
| Refund eligibility | Proposed changes for certain accumulated ITC on input services and capital goods | Could improve cash flow for qualifying businesses |
| Registration | Streamlined processing and clearer procedures | More predictable registration experience |
| Dispute resolution | Proposed improvements to notices, proceedings and selected refund-related matters | Greater clarity and more consistent processes |
| Compliance records | Better invoice-level and electronic statements | Easier reconciliation and audit preparation |
The practical effect will depend on the final legal provisions, system readiness and the conditions attached to each facility.
Businesses should therefore treat the period before implementation as an opportunity to improve their records, not as a reason to postpone compliance.
Official reference: 57th GST Council meeting recommendations, Press Information Bureau.
A major objective of the GST return reforms is to reduce differences between the tax liability reported in outward supply statements and the liability declared in GSTR-3B.
For many businesses, a mismatch is not necessarily the result of deliberate non-compliance. It may arise because an invoice was omitted, a credit note was entered incorrectly, a supplier amended a document, or a return was prepared using incomplete accounting data.
Nevertheless, unexplained discrepancies can lead to system-generated intimations, requests for clarification or further proceedings, depending on the circumstances.
The GST Council has recommended changes to help taxpayers report and correct these differences through more structured mechanisms. For a detailed look at the current position, read our guide to GST return mismatch notices.
GSTR-1 reports details of outward supplies. GSTR-3B is the summary return used to declare relevant tax liabilities and ITC and discharge tax.
The proposed changes aim to improve the consistency of the information reported in these forms.
For example, suppose a business reports taxable sales of ₹12 lakh in GSTR-1, but its GSTR-3B reflects a different amount. The difference could result from a missed invoice, a reporting error or an adjustment that needs explanation.
Under the proposed framework, a mechanism would enable reporting or correction of certain liability differences in GSTR-3B so that the figures align more appropriately with the details furnished through GSTR-1, GSTR-1A or the Invoice Furnishing Facility (IFF).
The intention is to reduce avoidable notices and make corrections more systematic.
GSTR-1A provides a facility to add or amend certain outward supply details after GSTR-1 has been filed, subject to applicable rules and timelines.
IFF is an optional facility available to eligible taxpayers under the QRMP scheme for furnishing specified outward supply details during the first two months of a quarter.
The Council recommended enhancements to GSTR-1, GSTR-1A and IFF to improve reconciliation with GSTR-3B.
Businesses should maintain accurate invoice records and monitor the official GST portal for instructions on any revised forms or processes.
Reverse charge applies to specified supplies for which the recipient, rather than the supplier, is responsible for paying GST under the applicable provisions.
Errors in reverse-charge reporting can affect both tax liability and the reporting of any related ITC.
The Council recommended an electronic statement covering tax paid under reverse charge and ITC claimed. The purpose is to help taxpayers report these transactions more accurately.
Businesses should maintain separate records for reverse-charge supplies, the tax paid and any corresponding ITC, subject to the applicable conditions.
The Council recommended that the alternative mechanism for correcting liability and ITC in GST returns be brought into force from the April 2027 return period.
The revised mechanism was also recommended for time-bound public consultation. Businesses should verify the final rules and effective dates before using any new correction facility.
Until then, taxpayers must follow the procedures legally applicable to their respective tax periods.
Input tax credit is one of the most important parts of GST compliance because it affects the amount of tax a business ultimately pays.
A business may pay GST on eligible purchases and claim credit against its output tax liability, provided it satisfies the applicable legal conditions.
However, ITC errors can arise when invoices are missing, suppliers report information incorrectly, credit notes are overlooked or the business claims credit that is restricted under the law.
The 2026 GST Council recommendations aim to improve the way ITC is reported, reconciled, reversed and reclaimed.
GSTR-2B is an auto-drafted statement that provides information relevant to a recipient's ITC based on information furnished by suppliers and other data available through the GST system.
The Council recommended a mechanism to help taxpayers correct ITC reported in GSTR-3B so that it aligns with the ITC made available in GSTR-2B.
This does not mean that every amount appearing in GSTR-2B automatically qualifies for credit. Businesses must continue to check the statutory conditions and restrictions applicable to each transaction.
Practical example: Suppose a business claims ₹2 lakh of ITC in GSTR-3B, while its GSTR-2B reflects ₹1.7 lakh of relevant credit.
The ₹30,000 difference should be investigated. It may involve a missing invoice, a supplier reporting issue, a timing difference, a duplicate claim or credit that is not eligible.
The business should identify the reason and determine the appropriate action under the rules applicable to that period.
ITC may need to be reversed in certain circumstances. In some cases, the law permits a later reclaim when the relevant conditions are satisfied.
If a business does not maintain proper records of reversals and reclaims, its return figures may become inconsistent or difficult to explain.
The Council recommended an electronic statement to help taxpayers track ITC reversed and reclaimed.
Businesses should begin maintaining a clear record of:
The original invoice and ITC amount.
The period in which credit was claimed.
The reason for reversal.
The amount reversed and the relevant return.
The event or condition allowing a possible reclaim.
The period and supporting evidence for any reclaim.
A reclaim should not be made simply because a difference has disappeared from a statement. The applicable legal conditions must be satisfied.
The Invoice Management System (IMS) allows recipients to review supplier-reported documents and take actions such as accepting, rejecting or keeping eligible documents pending, subject to the applicable framework.
The Council recommended further changes to support ITC reporting and reconciliation through IMS.
For businesses, this reinforces the importance of reviewing purchase invoices regularly rather than waiting until the return filing deadline.
Accounting teams should establish a process for checking supplier GSTINs, invoice numbers, taxable values, tax amounts, credit notes and the status of documents requiring follow-up.
The Council also recommended amendments to Section 17(5) of the CGST Act to remove restrictions on ITC for certain specified supplies. The announced recommendations included areas such as outdoor catering, health and life insurance, telecommunication towers, pipelines laid outside factory premises, free samples and goods destroyed or written off on expiry of shelf life as required by law.
These are proposed changes to the law, not a blanket permission to claim credit on every expense in these categories.
The exact eligibility, exceptions, effective dates and documentation requirements must be checked against the enacted amendments and applicable rules before a claim is made.
What businesses should do now: Keep category-wise purchase records and avoid changing ITC treatment solely on the basis of a Council announcement. Confirm the operative legal position for the relevant tax period.
Official reference: GST Council recommendations and ITC reforms.
GST refunds can be important for businesses that export goods or services, make qualifying zero-rated supplies, operate under an inverted duty structure or have excess balances in their electronic cash ledger.
When eligible refunds take time to process, businesses may experience working-capital pressure. The GST Council has therefore recommended a phased move towards more automated, system-based refund processing.
The proposals cover excess cash ledger balances, specified zero-rated supply refunds and refunds arising from an inverted duty structure.
The Council recommended the following measures for the first phase.
1. Automatic sanction of excess cash ledger refunds
Eligible refund claims relating to excess balances in the electronic cash ledger would be sanctioned automatically by the system without officer intervention.
This is intended to make the return of eligible excess cash balances more predictable.
2. Shorter acknowledgement or deficiency memo period
The proposed time limit for issuing an acknowledgement or deficiency memo would be reduced from 15 days to 10 days.
Where the proper officer does not issue either within 10 days, the system would provide for deemed acknowledgement under the proposed framework.
3. Provisional refund of up to 90% for specified claims
For eligible low-risk refund claims relating to zero-rated supplies and inverted duty structure, the system would provisionally sanction 90% of the amount claimed, based on risk identification and evaluation.
This is not a guarantee that every applicant will receive 90% of the claimed amount. Eligibility, system risk assessment and the final legal framework will determine the treatment.
The second phase proposes system-based acknowledgement after verification of refund applications.
For acknowledged claims relating to zero-rated supplies, the Council recommended automated sanction of the full eligible refund after adjusting pending dues, if any, and subject to the system's risk assessment.
The proposal is designed to reduce manual intervention while retaining checks for risk and compliance.
The Council also recommended changes to Form GST RFD-01 to capture information in a system-readable format and remove the requirement to upload scanned documents for specified zero-rated supply and inverted duty structure refund claims.
Other recommendations include removing a particular restriction on the maximum turnover of zero-rated supply of goods for calculating specified refunds and clarifying how the ₹1,000 minimum refund threshold applies across CGST, SGST or UTGST and IGST together.
These are proposed amendments and should not be treated as effective merely because they have been recommended. Taxpayers should confirm the operative rules and portal requirements before filing.
Official reference: GST Council recommendations on refund reforms.
Another important recommendation concerns accumulated ITC on input services and capital goods in specified refund situations.
Under the existing framework described by the government, the calculation of accumulated ITC refunds excludes certain categories of credit in particular cases. The Council recommended changes to allow broader refund eligibility, subject to the relevant conditions.
The Council recommended allowing specified ITC on input services to be included in the calculation of refunds under the inverted duty structure route for credit availed on or after 1 November 2026.
An inverted duty structure can arise when the GST rate on inputs is higher than the rate on the outward supply, leading to accumulated credit, subject to the statutory framework.
This proposed change may be relevant to manufacturers and other qualifying businesses that incur substantial input service costs.
The Council recommended allowing specified ITC on capital goods to be included in the calculation of refunds for zero-rated supplies and inverted duty structure cases.
The proposal provides for the relevant capital goods ITC to be spread over 60 months and to apply to eligible credit availed on or after 1 April 2027.
This is particularly relevant to businesses investing in machinery, equipment and other qualifying capital assets.
Consider a manufacturer that invests in equipment and accumulates ITC while making qualifying zero-rated supplies. The proposed change could allow eligible capital goods credit to be included in the relevant refund calculation, spread over the specified period.
However, eligibility is not automatic. Businesses must check the final amendments, the calculation method, the applicable tax period and all relevant conditions.
Important: The dates above come from the GST Council's recommendations. Before filing a refund claim, verify that the relevant amendments and rules have been brought into force.
Registration-related reforms are another part of the wider GST process improvement agenda.
For businesses, registration issues can delay operations, create uncertainty when expanding into another state and affect the ability to comply with GST obligations on time.
The Council recommended streamlining the registration process with clearer guidelines for filing and processing applications.
The recommendations build on measures relating to simplified registration, including the existing Rule 14A framework for eligible applicants who do not intend to pass on ITC beyond the prescribed monthly threshold.
The Council also discussed further improvements to processing applications in other cases.
Ensure the business name, PAN, address and other details are consistent across records.
Maintain accurate proof of principal place of business and additional places of business, where applicable.
Keep bank and identity documents ready where required.
Monitor registration applications and respond promptly to lawful requests for additional information.
Review registration details before making changes to the business structure, address or operations.
Confirm the applicable registration and amendment procedures on the official GST portal.
The Council also recommended measures intended to simplify GST registration for small sellers operating through e-commerce platforms.
The recommendations include facilitating the use of an e-commerce operator's warehouse as a principal place of business in a state or Union Territory where the seller has no physical presence, subject to the proposed framework.
Small sellers planning to expand across states should follow the official rules and portal guidance before relying on this facility.
The purpose of these proposals is to make registration procedures more predictable. They do not eliminate the need to satisfy the legal conditions for registration or to maintain accurate taxpayer information. If you are planning a new registration, read our guide to GST Registration in Delhi India.
A GST discrepancy can develop into a dispute if the taxpayer and the department disagree about the tax treatment, eligibility for credit, declared liability or supporting documents.
The Council recommended broader process reforms intended to improve consistency and reduce avoidable disputes, including common standards for GST notices and proceedings.
For taxpayers, clearer notices and more consistent procedures can make it easier to understand the issue and respond with relevant evidence.
However, businesses should not assume that every notice will disappear or that the reforms automatically remove tax liabilities. Related reading: GST Notice Rules 2026 and GST Appeal 2026.
First, identify the communication. Determine whether it is an intimation, a request for information, a scrutiny-related communication or a formal show-cause notice.
Second, check the legal provision and deadline. Record the relevant financial year, tax period, amount and response date.
Third, reconcile the figures. Compare the notice with GSTR-1, GSTR-3B, GSTR-2B, invoices, accounting records and payment details, as relevant.
Fourth, prepare a documented explanation. Explain each discrepancy and attach evidence that directly supports the response.
Fifth, correct genuine errors through the proper route. The available correction method depends on the type of error, the tax period and the law currently in force.
Finally, retain proof of submission. Keep the acknowledgement and a copy of the response.
If a notice involves substantial tax, disputed ITC, allegations of suppression or formal adjudication, consider obtaining advice from a qualified GST professional or tax lawyer.
Businesses do not need to wait for every proposed reform to take effect before improving their compliance processes.
A well-organised GST system can reduce errors under the current framework and make it easier to adapt when new mechanisms become available.
Reconcile the sales register with GSTR-1.
Compare GSTR-1 figures with GSTR-3B and explain differences.
Reconcile purchase invoices with GSTR-2B.
Check supplier GSTINs, invoice numbers, tax values and credit notes.
Review ITC eligibility and blocked-credit restrictions.
Record ITC reversals and any eligible reclaims.
Reconcile reverse-charge liability and related ITC.
Verify tax payments and electronic ledger balances.
Check the applicable return deadlines and filing status.
Maintain supporting invoices, statements and reconciliation reports.
In addition to monthly work, businesses should review:
Registration details and changes in business operations.
Refund claims and supporting documentation.
Export records and zero-rated supply documentation, where relevant.
Outstanding notices, demands and appeals.
Unresolved supplier discrepancies.
Accounting software and GST portal reconciliation processes.
Staff responsibilities for return preparation and review.
Businesses should pay particular attention to the proposed return correction mechanism.
Before implementation, consider whether your accounting system can identify invoice-level differences, track amendments and retain an audit trail of ITC reversals and reclaims.
Ask your accountant or GST service provider how the proposed forms and electronic statements may affect the existing workflow. Confirm the final rules and system instructions before changing filing practices.
Assuming every recommendation is already law: GST Council recommendations may require amendments, notifications, rules and technical implementation. Always verify the operative position before relying on a proposed benefit.
Claiming ITC without sufficient checks: The presence of an invoice in a statement does not by itself establish that all legal conditions for credit are satisfied.
Ignoring return mismatches: Unexplained differences can become harder to resolve when records are incomplete or several tax periods are involved.
Treating a proposed refund as guaranteed: Automated processing and provisional refunds remain subject to the relevant eligibility rules, risk assessment and implementation framework.
Filing refund claims without proper documentation: Even where the process becomes more automated, businesses should retain accurate invoices, export records, calculations and supporting evidence.
Failing to update accounting procedures: New electronic statements and reconciliation mechanisms may require changes to internal controls, software settings and review procedures.
Using an incorrect correction method: The available route depends on the relevant return, tax period and legal provisions. Do not assume a proposed mechanism can be used for an earlier period without confirmation.
Keeping up with GST compliance can be challenging for startups, traders, manufacturers and growing businesses. Registration, return preparation, invoice reconciliation and notice management may involve different requirements and authorities.
Legal Info India provides business registration-related services, including assistance with GST registration, company registration and MSME registration. We also support businesses with trademark registration and other registration-related needs.
Our team can help businesses understand relevant registration requirements and identify documentation issues to address while setting up or expanding operations.
Explore our GST and business registration services or visit Legal Info India.
For detailed return reconciliation, refund claims, disputed ITC, tax demands or formal GST proceedings, seek assistance from a suitably qualified GST practitioner, chartered accountant or tax lawyer, depending on the issue.
Press Information Bureau: Recommendations of the 57th Meeting of the GST Council, 8 October 2026
Press Information Bureau: Next-Gen GST Process Reforms
GST Council: Official website and latest updates
CBIC GST: GST laws, rules and notifications
GST Portal: Returns, registration and taxpayer services

The proposed GST Compliance Changes 2027 reflect a move towards better return reconciliation, more automated refund processing and clearer procedures for registration and compliance.
For businesses, the most significant developments include a proposed mechanism to correct certain GSTR-1 and GSTR-3B liability differences, improved alignment of ITC with GSTR-2B, electronic tracking of reversals and reclaims, and phased refund processing for specified claims.
The recommendations on accumulated ITC refunds and certain blocked-credit categories may also be important for qualifying businesses. However, the actual benefit will depend on the final legal provisions, eligibility requirements and effective dates.
Businesses should not wait until April 2027 to improve their systems. Start by reconciling returns regularly, maintaining invoice-level records, following up with suppliers, reviewing refund documentation and monitoring official notifications.
The best preparation is accurate recordkeeping, timely compliance and a clear understanding of which rules are currently in force.
For business registration assistance and related compliance support, visit Legal Info India or explore our services.
The proposed changes include improved GST return reconciliation, mechanisms for correcting certain liability and ITC mismatches, phased automated refund processing, proposed expansion of refund eligibility for specified input services and capital goods, and registration and dispute-related process improvements.
The GST Council recommended that the alternative mechanism for correcting liability and ITC in returns be brought into force from the April 2027 return period. Taxpayers should confirm the final notifications and implementation instructions before relying on it.
The Council recommended phased system-based refund processing for specified categories. Proposals include automatic sanction of eligible excess cash ledger refunds and provisional refunds for specified low-risk zero-rated supply and inverted duty structure claims. The exact operation depends on the final rules and implementation.
The Council recommended changes affecting specified blocked-credit categories and the calculation of accumulated ITC refunds in certain cases. These proposals do not create an unrestricted right to claim all ITC. Businesses must verify the applicable amendments, conditions and effective dates.
The Council recommended including specified capital goods ITC in refund calculations for zero-rated supplies and inverted duty structure cases, with the relevant credit spread over 60 months. The recommendation applies to eligible capital goods ITC availed on or after 1 April 2027, subject to implementation of the required legal changes.
The Council recommended allowing specified input services ITC in the calculation of inverted duty structure refunds for credit availed on or after 1 November 2026. Businesses should check the operative provisions and refund calculation requirements before filing.
The reforms aim to reduce avoidable mismatches and system-generated communications. They do not guarantee that all notices will stop. Incorrect reporting, ineligible ITC, unpaid tax and other compliance issues may still require explanation or formal proceedings.
Yes. Businesses can improve invoice matching, supplier follow-up, ITC eligibility checks, reversal records and return reconciliation now. These controls will help under the existing framework and make it easier to adapt to future changes.
Not necessarily. A GST Council recommendation may require amendments to the CGST Act, CGST Rules, notifications, circulars or portal changes. Check official sources for the legal status of each measure before applying it to a transaction or return.
Businesses should monitor the GST Council website, the CBIC GST website and the GST Portal for official recommendations, notifications, rules, circulars and operational instructions.
We prioritize understanding your unique situation & offer tailored strategies that align with your goals,
don't navigate the legal maze alone – schedule.

Call Us 24/7
+91 9999 860 803
Call Us 24/7
+91 8527 406 788
Mail Us Anytime
info@legalinfoindia.in
Mail Us Anytime
nrandassociate@gmail.com
© Copyright 2025 LegalInfoIndia
Developed By:Vairina Infotech


 28 Oct 2026 (Last updated: 31 Oct 2026)